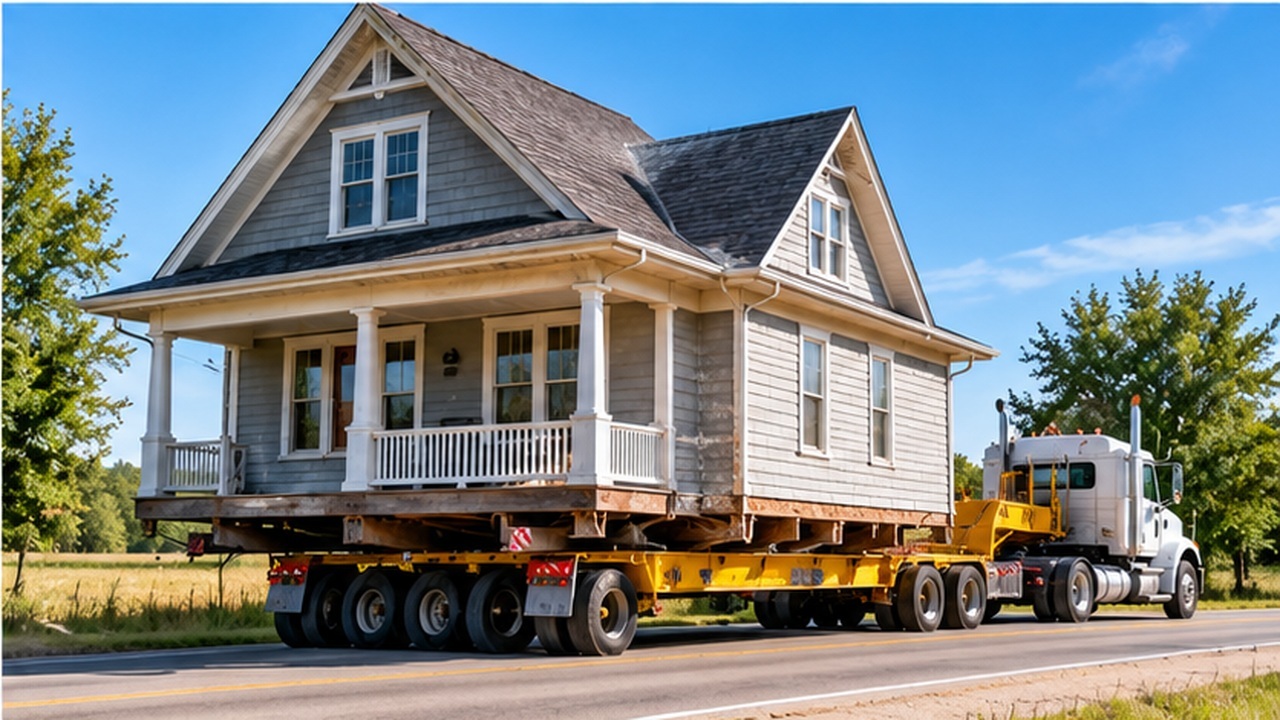
 Most buyers assume that the home they are purchasing has always been located on its current property. However, some houses have been physically relocated from one location to another.
Whether a historic home was preserved by moving it or an existing structure was transported to a new lot, the property’s relocation history can create unique questions during the mortgage process.
Why Would Someone Move an Entire House?
Moving an existing home is more common than many people realize, particularly in areas where older houses are preserved or land is being redeveloped.
Instead of demolishing a structure, an owner may hire specialized contractors to lift the house, transport it, and place it on a new foundation.
In other situations, a house may be relocated to make room for construction or to preserve a building with historical significance.
Although the home may look completely normal once the project is finished, its relocation history can still be relevant when applying for financing.
The Foundation Can Be an Important Factor
When a home is moved, it generally must be placed on a suitable foundation at its new location.
Mortgage lenders and appraisers may need to evaluate whether the foundation and structure meet applicable requirements.
Depending on the property and loan program, additional documentation may be requested regarding the foundation, building permits, inspections, and completed relocation work.
Buyers should not assume that a home is automatically eligible for financing simply because it has been occupied since the move.
Property Records May Need Clarification
A relocated house may have a construction history that differs from the records associated with its current lot.
For example, the house may have been originally built decades earlier but moved to its present location much more recently.
The lender or appraiser may need to understand the difference between the original construction date and the date of relocation.
Permit records, certificates of occupancy, and other local documentation may help establish that the relocation was completed appropriately.
Missing or inconsistent information could lead to additional questions before the mortgage is approved.
Appraising a Relocated Home
Determining market value may also require careful consideration.
The appraiser evaluates the property in its current location and condition, rather than relying solely on what the structure may have been worth before it was moved.
Factors such as the foundation, overall condition, neighborhood, available comparable sales, and quality of completed work can influence the valuation.
A relocated house is not automatically worth less, but unusual property characteristics may require additional analysis.
What Buyers Should Do Before Applying
Buyers interested in a relocated home should ask when the move occurred, who performed the work, and what documentation is available.
They should also discuss the home’s history with their mortgage professional before committing to a financing timeline.
For buyers who appreciate unique or historic properties, a relocated home can offer considerable charm. The key is understanding the property’s history and confirming that its current condition and documentation support the intended mortgage financing.
