Wendy M. Doerzbacher

Nationwide Mortgage Bankers

  • Home
  • About
    • About Wendy
    • Privacy Policy
    • Accessibility Statement
  • Resources
    • First Time Seller Tips
    • First Time Buyer Tips
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage FAQ
    • Mortgage Glossary
    • Mortgage FAQ
    • Mortgage Glossary
  • Mortgage Calculator
  • Blog
  • Contact Wendy

How Inflation Can Affect Homebuyers

August 18, 2026 by Wendy Doerzbacher

Inflation affects far more than the price of groceries and gasoline. It can also influence mortgage rates, household budgets, home prices, and the amount of money buyers feel comfortable spending. Understanding how inflation connects to the home-buying process can help you make decisions based on your complete financial picture rather than focusing on only one number.

Inflation Can Influence Mortgage Rates

When inflation remains elevated, borrowing costs may rise as financial markets respond to changing economic conditions. Mortgage rates do not move in perfect step with inflation, but inflation expectations can influence the bond market that helps shape mortgage pricing. A higher rate can increase the monthly payment associated with the same loan amount.

Everyday Expenses Affect Buying Power

Higher prices for food, transportation, utilities, insurance, and other essentials can reduce the amount available for housing each month. Before deciding how much home to buy, review your current spending and allow room for expenses that may continue changing. A payment that technically fits a lender’s guidelines should also feel manageable within your real-life budget.

Home Prices May Respond Differently by Market

Inflation does not affect every housing market in the same way. Construction costs, available inventory, employment growth, and local demand can influence whether home prices rise, level off, or become more negotiable. Your real estate and mortgage professionals can help you evaluate conditions in the specific area where you plan to buy.

Preparation Creates More Flexibility

Strengthening your credit, reducing unnecessary debt, increasing savings, and comparing loan options can help you remain prepared in an uncertain economy. It is also helpful to understand the difference between the maximum amount you may qualify to borrow and the payment that supports your other financial goals.

Consider the Full Cost of Ownership

Inflation may also affect expenses that continue after closing, including utilities, repairs, maintenance materials, property insurance, and professional services. Building those costs into your plan can provide a more realistic view of affordability. Leaving room in the budget for future price changes may be more valuable than using every dollar available for the monthly mortgage payment.

Inflation can change the cost of buying and owning a home, but it does not automatically mean you should postpone your plans. By reviewing your budget carefully, understanding current financing conditions, and focusing on long-term affordability, you can make a confident decision that works in both today’s economy and the years ahead.
Filed Under: Mortgage Tips Tagged With: Home Buying, Inflation, Mortgage Tips

What’s Ahead For Mortgage Rates This Week – August 17th, 2026

August 17, 2026 by Wendy Doerzbacher

Both the Consumer Price Index (CPI) and Producer Price Index (PPI) reported figures that were either entirely in line with expectations or just slightly below them. This does not set any new precedent for the potential of a rate increase from the Federal Reserve, as inflation is still rising, just at a largely expected rate.

Retail sales have also shown signs of a slump compared to previous quarters, with gas prices and Amazon Prime Day among the primary culprits. This isn’t necessarily a broader indicator of overall economic health, but there is certainly pressure being felt from persistent inflation across both consumer and manufacturing sectors.

Consumer Price Index
CPI increased 0.1% m/m (3.4% y/y) following a 0.4% monthly decline in June. The core index rose 0.2% after having been unchanged in June. The Action Economics Forecast Survey expected a 0.1% monthly gain for the headline index and a 0.2% monthly increase for the core index. The 3-month rate for the headline index fell to 0.5% annualized in July from 2.8% in June while the 3-month rate for the core index slipped to 1.6% from 2.3% in June.

Producer Price Index
The producer price index, a measure of underlying inflation pressures, was unchanged for the month, below the 0.2% Dow Jones consensus estimate and after falling 0.1% in June. The June figure was revised from a previously reported decline of 0.3%. Excluding food and energy, the core PPI rose 0.2%, against the forecast for a 0.3% gain. The core PPI excluding trade services increased 0.4%.

Primary Mortgage Market Survey Index

  • 15-Year FRM rates saw a decrease of -0.05%, bringing the current rate to 5.96%.
  • 30-Year FRM rates saw a decrease of -0.02%, bringing the current rate to 6.67%.

MND Rate Index

  • 30-Year FHA rates saw an increase of 0.01%, with current rate at 6.29%.
  • 30-Year VA rates saw an increase of 0.01%, with current rate at 6.31%.

Jobless Claims
Initial Claims were reported to be 209,000 compared to the expected claims of 204,000. The previous week landed at 199,000.

What’s Ahead
A very light release week proceeding the inflation data, with only the economic leading indicators having any outsized influence.

Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

How Mortgage Payments Change Over the Life of Your Loan

August 14, 2026 by Wendy Doerzbacher

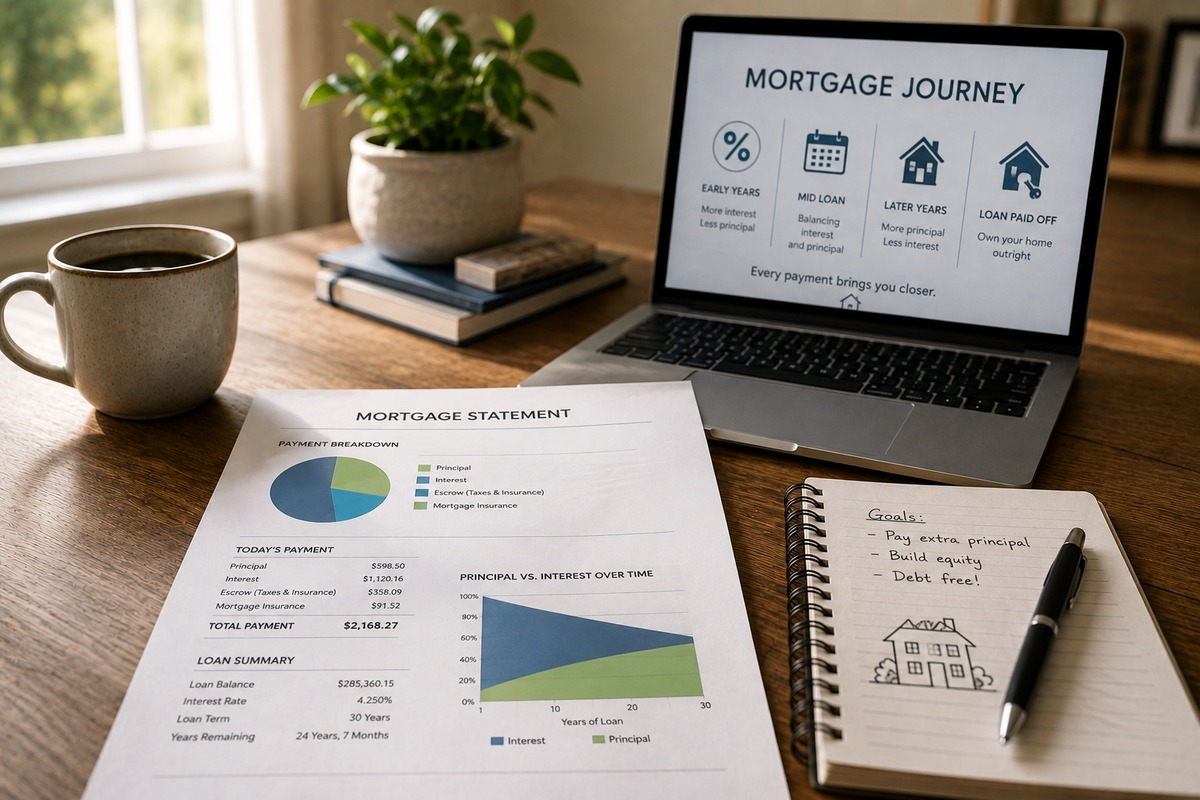
A mortgage payment may look consistent from month to month, but the way that payment works changes throughout the life of the loan. Understanding how principal, interest, escrow, and other costs evolve can help homeowners read statements more confidently and see the progress they are making over time.

Principal and Interest Shift Over Time

With a typical fixed-rate amortizing mortgage, the combined principal-and-interest payment remains the same. Early in the loan, a larger portion generally goes toward interest because the outstanding balance is higher. As the balance declines, more of each payment is applied to principal.

Escrow Can Change the Total Payment

Property taxes and homeowners insurance are separate from the fixed interest rate. If these expenses are collected through escrow, changes in tax bills, insurance premiums, or escrow shortages can increase or decrease the total monthly payment even when principal and interest remain stable.

Mortgage Insurance May Eventually End

Some borrowers pay mortgage insurance based on their loan type and down payment. Depending on the program and applicable rules, this cost may be eligible for cancellation after certain requirements are met, while other forms may remain for the life of the loan unless the mortgage is refinanced.

Extra Payments Affect the Timeline

Additional principal payments can reduce the outstanding balance and shorten the payoff period when applied correctly. They generally do not automatically change the scheduled monthly payment, but they may reduce the total interest paid over the life of the loan. Homeowners should confirm how their servicer applies extra funds.

Your mortgage is not static, even when the interest rate is fixed. The balance declines, the principal-and-interest mix changes, and taxes, insurance, or mortgage insurance may alter the total payment. Reviewing your statements regularly helps you understand these changes and track your progress toward owning the home outright.

Filed Under: Mortgage Tips Tagged With: Amortization, Homeownership, Mortgage Tips

  • « Previous Page
  • 1
  • …
  • 14
  • 15
  • 16
  • 17
  • 18
  • …
  • 645
  • Next Page »

Wendy Doerzbacher Headshot

Wendy M. Doerzbacher


LOAN OFFICER
Nationwide Mortgage Bankers Inc
Call (516) 982-6339
NMLS# 12985

How can I help?


0 / 180

Connect with Me!

Archives

Browse articles by category

Recent Articles

  • What Happens When the Home You Want Is on a Private Road?
  • Why Unpermitted Renovations Can Create Problems During Mortgage Approval
  • Can You Finance a Home That Has a Second House on the Property?
  • What’s Ahead For Mortgage Rates This Week – October 19th, 2026
Nationwide Mortgage Bankers, Inc NMLS# 819382 (www.nmlsconsumeraccess.org) Equal Housing Lender
68 S Service Rd Suite 400, Melville, NY 11747 | (833) 700-8884 | www.nmbnow.com; “NMBNOW” “Americasa” and “Americasa Home Loans” are registered DBAs of Nationwide Mortgage Bankers, Inc (“NMB”). “Americasa” is not a DBA approved in New York but “Americasa Home Loans” is. NMB is in no way affiliated with “Nationwide Mutual Insurance Company”.

Our Location


68 S Service Road, Suite 400
Melville, NY, 11747

Equal Housing Lender

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in